
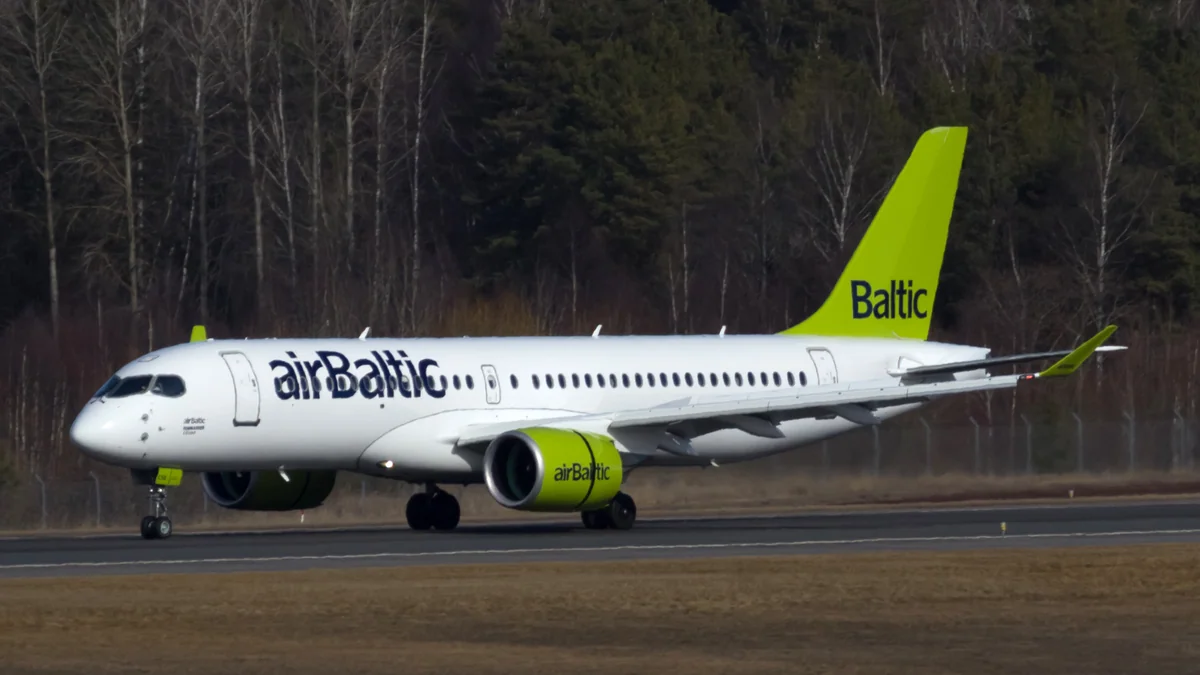
A national flag carrier often represents the ultimate synthesis of state prestige and economic reach, yet today, Latvia’s crown jewel finds itself seeking refuge in the clinical legal corridors of a Manhattan court. On September 14, 2026, Air Baltic formally initiated a debt restructuring process under Chapter 11 of the U.S. Bankruptcy Code, a strategic pivot necessitated by S&P’s decision to downgrade the airline’s credit rating to “selective default.” This move marks a profound rupture in the emerging paradigm of state-owned enterprises, where the shield of national identity no longer provides immunity from the gravity of global capital markets.
The Anatomy of Restructuring and the High Price of Capital
In the current global landscape, we are witnessing a fundamental rewriting of the old order, where institutional boundaries between state-backed stability and market volatility are blurring. The decision to seek Chapter 11 protection is a calculated “breathing space” that allows Air Baltic to maintain its flight schedules and passenger trust without the immediate threat of asset seizure—a legal mechanism that the fragmented European legal framework often fails to provide with similar efficacy. It is a moment where legal form must subserviently follow commercial substance to ensure basic survival.
However, this selective default status reveals a deep-seated institutional crisis, where the cross-border correlation between ambitious expansion and actual liquidity has become dangerously uncoupled. If the Latvian state’s guarantee once acted as a financial talisman, it is now clear that such guarantees do not translate into immunity when facing global creditors. The following months will test whether the peace secured in a New York courtroom can be converted into a new socio-economic blueprint for the airline’s survival.
Today, the airline’s aviation ambitions are colliding with a balance-sheet reality where book value is evaporating faster than the fleet can be modernized. To address years of accumulated losses, the Latvian government has sanctioned a massive capital reduction of €571.29 million. This fiscal surgery is a prerequisite for any eventual partial privatization, yet it occurs against a backdrop of a deepening liquidity crunch that makes new bridge financing a prohibitively expensive privilege.
The market’s assessment of this institutional behavior has been unforgiving. To sustain operations, the company has secured €350 million in new loans, but the cost is staggering: interest rates are estimated to range from 12% to an extreme 25% per annum. This is not the interest rate of a stable regional player; it is the rate of a high-stakes gamble in a volatile market. The bond markets have been equally merciless, with the 14.5% bonds issued in 2024 trading at a 93% discount, signaling that the financial world has effectively devalued the airline’s previous promises.
While a €257 million interim financing deal was reached in September 2026, the terms reflect a company in a state of pure survival rather than strategic growth. We are observing a scenario where financial acrobatics are being used to stave off collapse, but the question remains: is this sustainable vitality or merely the prolongation of an institutional struggle? In the Estonian context, we must recognize that when national symbols are forced to submit to the harsh laws of global capital, the taxpayer often ends up funding the transition from one crisis to the next.
National pride is the most expensive grade of fuel in aviation; it provides a sense of lift, but it cannot guarantee a safe landing.
The Post-Gauss Era: Management in the Shadow of the State
The image of the autonomous, Western-style corporate entity has shifted toward a model of total state dependency. With the Latvian government now controlling 97.97% of the shares, the airline has effectively been re-nationalized—a paradoxical outcome for a company that spent years positioning itself for private investment. This high level of state control suggests that Air Baltic is now being treated as a strategic infrastructure project rather than a commercial business venture.
The departure of long-term CEO Martin Gauss in April 2025 marked the end of an era defined by aggressive visionary growth. Gauss, who successfully built Air Baltic into a recognized global brand, eventually succumbed to the laws of financial gravity. His exit was a necessary political concession to calm domestic critics, but it left a strategic vacuum that the current acting CEO, Pauls Calitis, must now navigate.
When leadership shifts from a visionary to a technocrat, the socio-economic blueprint usually moves from expansion to painful consolidation. Calitis must operate within the narrow corridors defined by New York courts and Latvian political circles. Every financial decision now requires both political clearance and legal validation, a dynamic that risks stifling the very agility needed to survive in the competitive European sky. If the state cannot eventually hand back the controls to professional, independent management, the Latvian taxpayer risks being trapped in a cycle of permanent subsidies.
Strategic Skepticism: The View from Tallinn
Estonia was recently offered a front-row seat to this unfolding drama, with a ticket price that seemed remarkably low given the scale of the production. In July 2025, the Estonian government was presented with the opportunity to acquire a 10% stake in the regional giant for a mere €14 million. From the Stenbock House, the response was one of cold, pragmatic refusal—a decision that looks increasingly prescient in light of current events.
Minister of Infrastructure Kuldar Leis’s skepticism was rooted in a clear understanding of regional institutional behavior. When a balance sheet resembles a river disappearing into the sand, no entry price is low enough. Tallinn was unwilling to engage in a neighbor’s financial rescue operation without a real right of veto, correctly identifying the restructuring that was already inevitable. The fear of repeating the “Nordica scenario”—where national pride led to a capital-intensive dead end—was a primary driver of this caution.
By choosing skepticism over sentimentality, Estonia has maintained its position as a safe observer rather than a direct victim of the airline’s financial turbulence. This raises a critical question about the future of Baltic cooperation: are we capable of a unified aviation strategy, or has trust been permanently replaced by a posture of legal and fiscal self-protection? In the Estonian context, the avoidance of this investment was not just a budgetary decision, but a strategic refusal to subsidize another nation’s regional ambitions.
The Veto and the Future Roadmap
The airline’s aspirations for a public debut have now met the icy pragmatism of the market, with the Initial Public Offering (IPO) frozen indefinitely. This pause is more than just a tactical delay; it is a symptom of a fundamental deficit in investor confidence. The focus has now shifted toward finding a strategic investor who can provide not just capital, but a sustainable path forward.
Historical precedents suggest that in these scenarios, larger European aviation groups often absorb smaller, restructured players. However, the Latvian government is attempting to defy this pattern by insisting on a “strategic veto” model—retaining at least 25% plus one share even after an eventual IPO. This is an attempt to ensure that Air Baltic does not become a mere feeder-service for global hubs, but maintains its role as a controller of regional transport corridors.
The survival course under Chapter 11 will require systemic cuts that go far beyond paperwork. By the summer of 2027, Air Baltic plans to significantly reduce its number of low-profit routes, moving toward a model where every flight must justify its existence on the ledger. This shift from volume to value is the only way to clean the balance sheet of the burden of empty seats.
Ultimately, the conclusion of the New York proceedings will determine if Air Baltic emerges as a leaner, independent success story or merely as a statistical unit in a consolidating European sky. For the state, the strategic question remains: at what point does the cost of maintaining a national symbol outweigh the functional benefit of the infrastructure? The answer will be written in the final filings of the Chapter 11 process, but the era of consequence-free regional ambition is officially over.